

Every week I’ll provide updates on the latest trends in cloud software companies. Follow along to stay up to date!
The Diffusion Gap
Andrej Karpathy had a really interesting post on X over the weekend:


Here’s the tweet in a visual funnel format
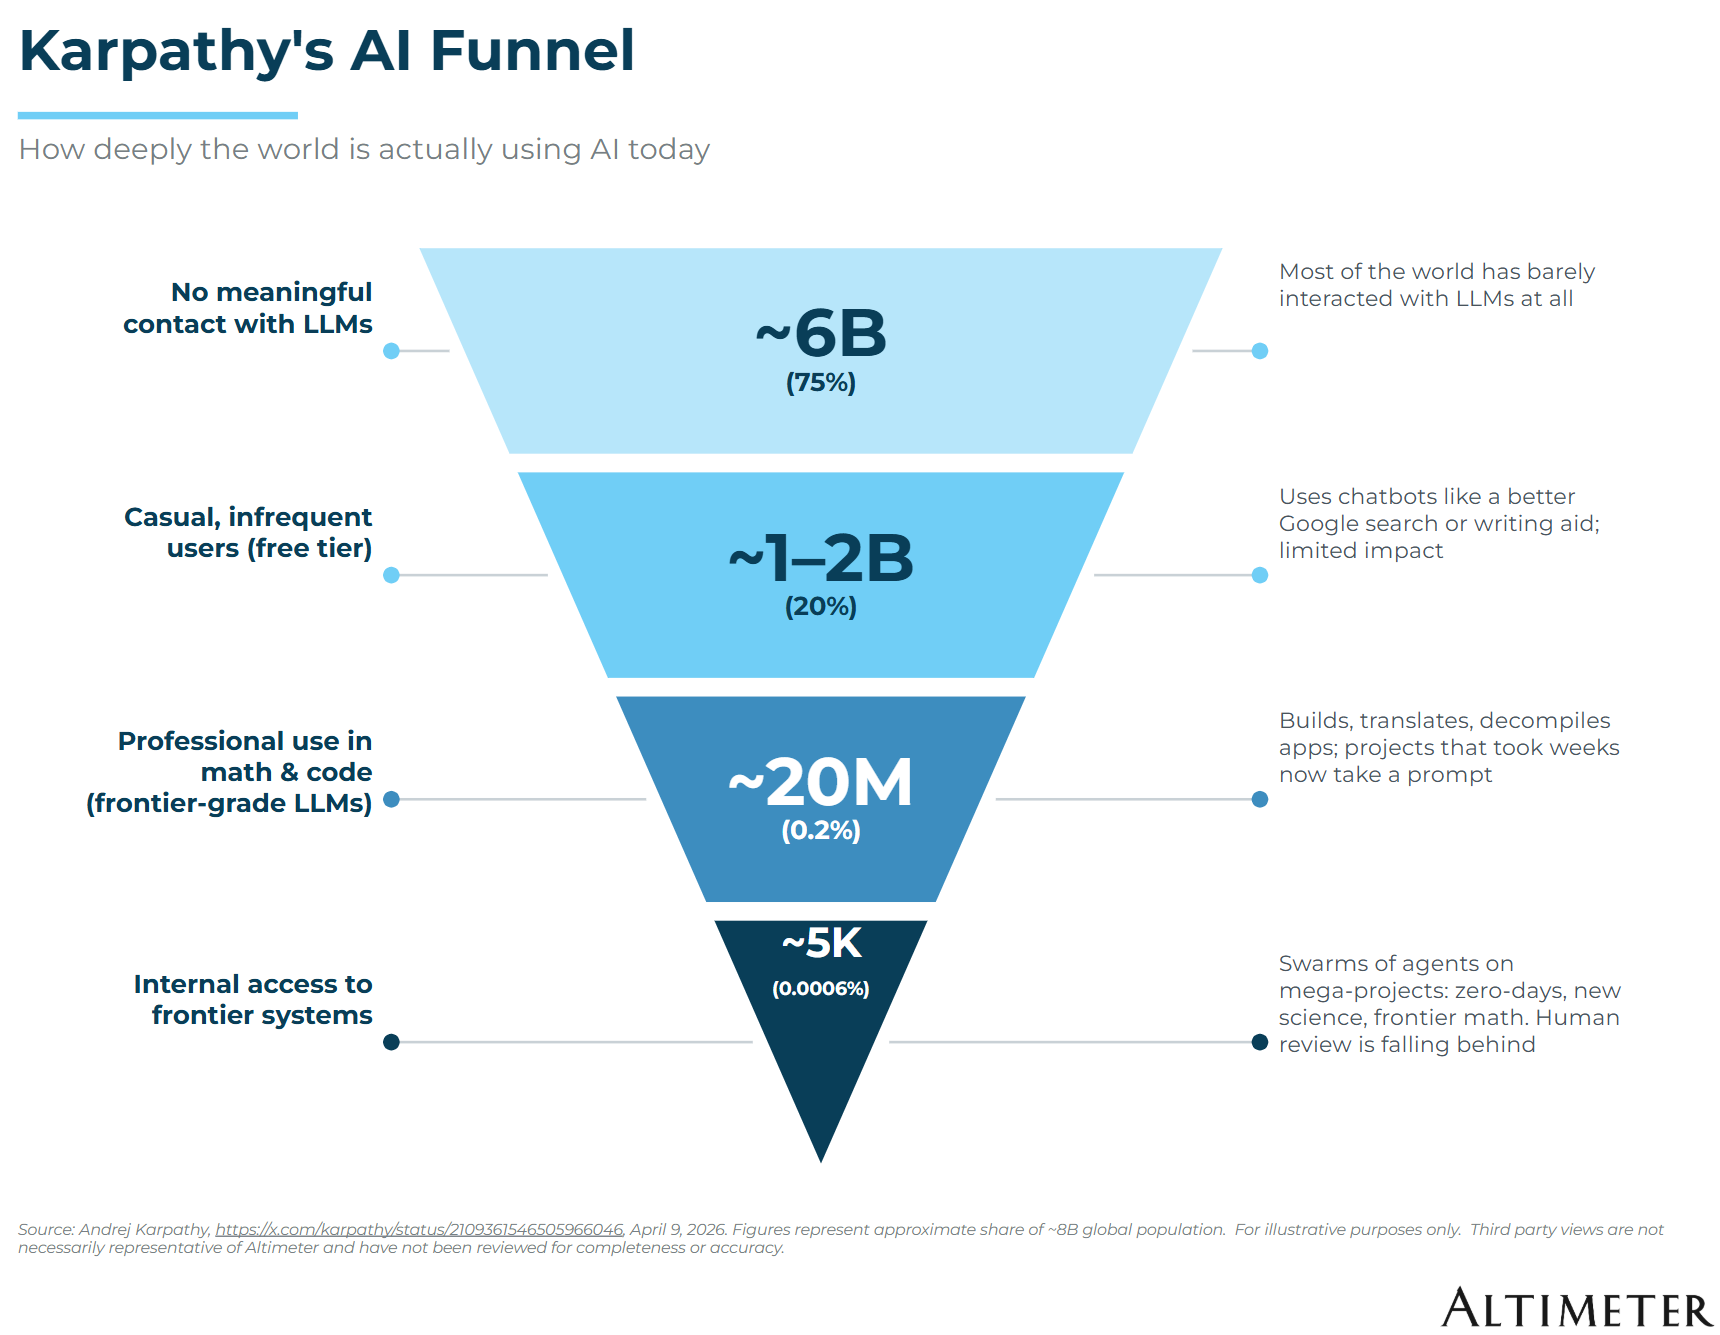
I think this diffusion question is a really important one. In particular, how quickly does AI diffuse? What Karpathy’s X post shows (in his opinion) is that diffusion is happening slower. PNC research shows that only ~2% of US households are paying for some sort of AI service.
What is the diffusion gap? It’s the delta between what you can accomplish with models (ie how powerful they are) and how the average person uses models.
Here’s why I think it matters. A big question in the market today is “will the revenues match the promised CapEx commitments.” It’s a big reason why all the semi-cap stocks got clobbered this week, and questions like “Will Coreweave go bankrupt?!” have been repeated over and over again online. The heavy early adopters clearly drive a ton of spend. And for this early adopter group, their spend seems to jump meaningfully as model progress continues. Check out the graph below posted from OpenAI. You can see usage inflect for the power users and median users (OpenAI users will clearly be categorized as overall power users relative to rest of the world)
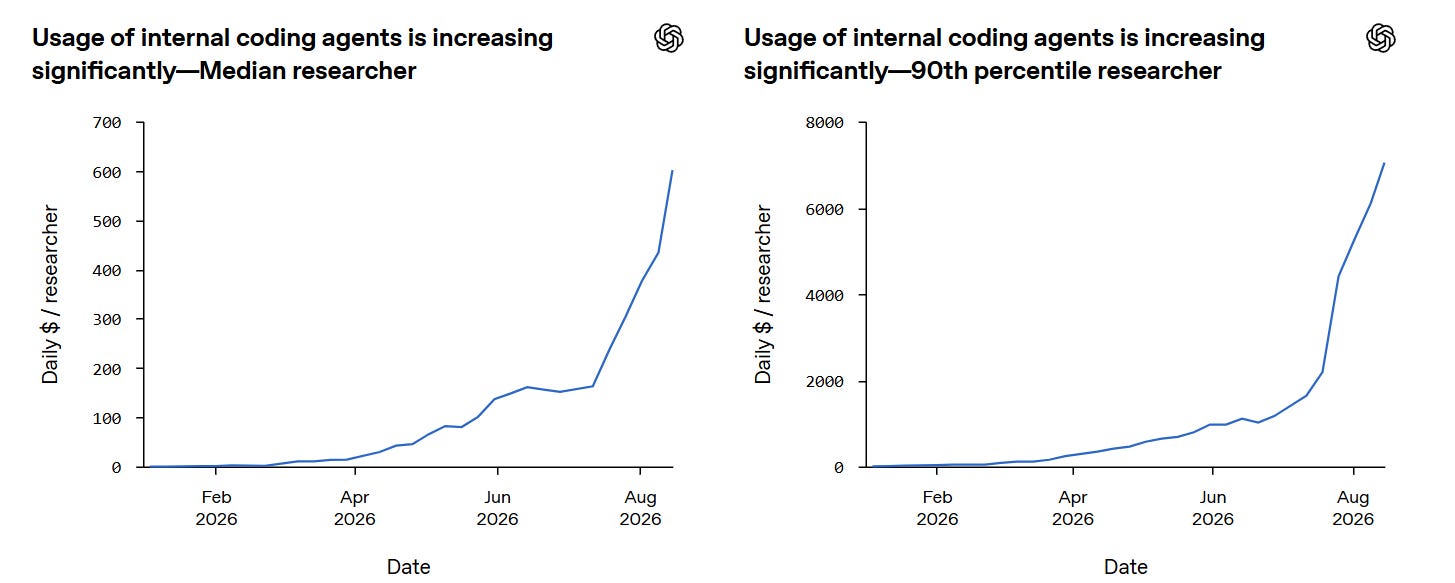
But the “average” user is lagging behind. So to answer the question of “will the revenues match the capex obligations” you either believe that the power users will continue to spend more and more, or the “average” spender will start to catch up. Or both. I think for the market to really gain confidence, we need the latter to happen (the average user starts using / spending more on AI).
So I see two paths on diffusion. Either it takes a bit longer (the blue dotted line below), or diffusion / spend follows a typical S-Curve. And this applies both to business and consumer users.
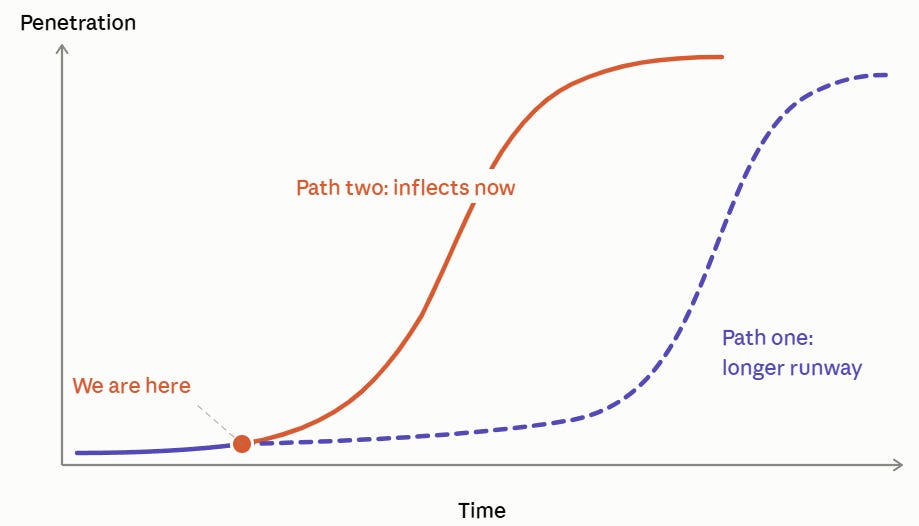
So which path do I think we take? Probably something in the middle, BUT something that looks a lot more like the orange line than the blue line. Why do I think this? Typically big diffusion gaps in tech have all closed in a similar fashion - the end user doesn’t get more sophisticated, but the tools get easier and easier to use and abstract away the complexity. I think I talked about this a few weeks ago with Muse / Instinct vs OpenClaw. OpenClaw was super popular among power users. But it didn’t really diffuse. Then Muse / Instinct and other personal agents exploded! Really these were “OpenClaw wrappers” (so much more than that, but for the sake of the argument let’s call them that). Muse / Instinct were technology that let averages users stay “unsophisticated” but start to adopt the technology.
Kind of similar to the internet. People didn’t learn how to use the internet in a terminal - they got a browser and THEN internet usage exploded. People didn’t learn how to use GPS, they got Google Maps. I think we’re starting to see the technology layers around the models really start to inflect which will allow the average users usage to inflect (and thus help close the diffusion gap).
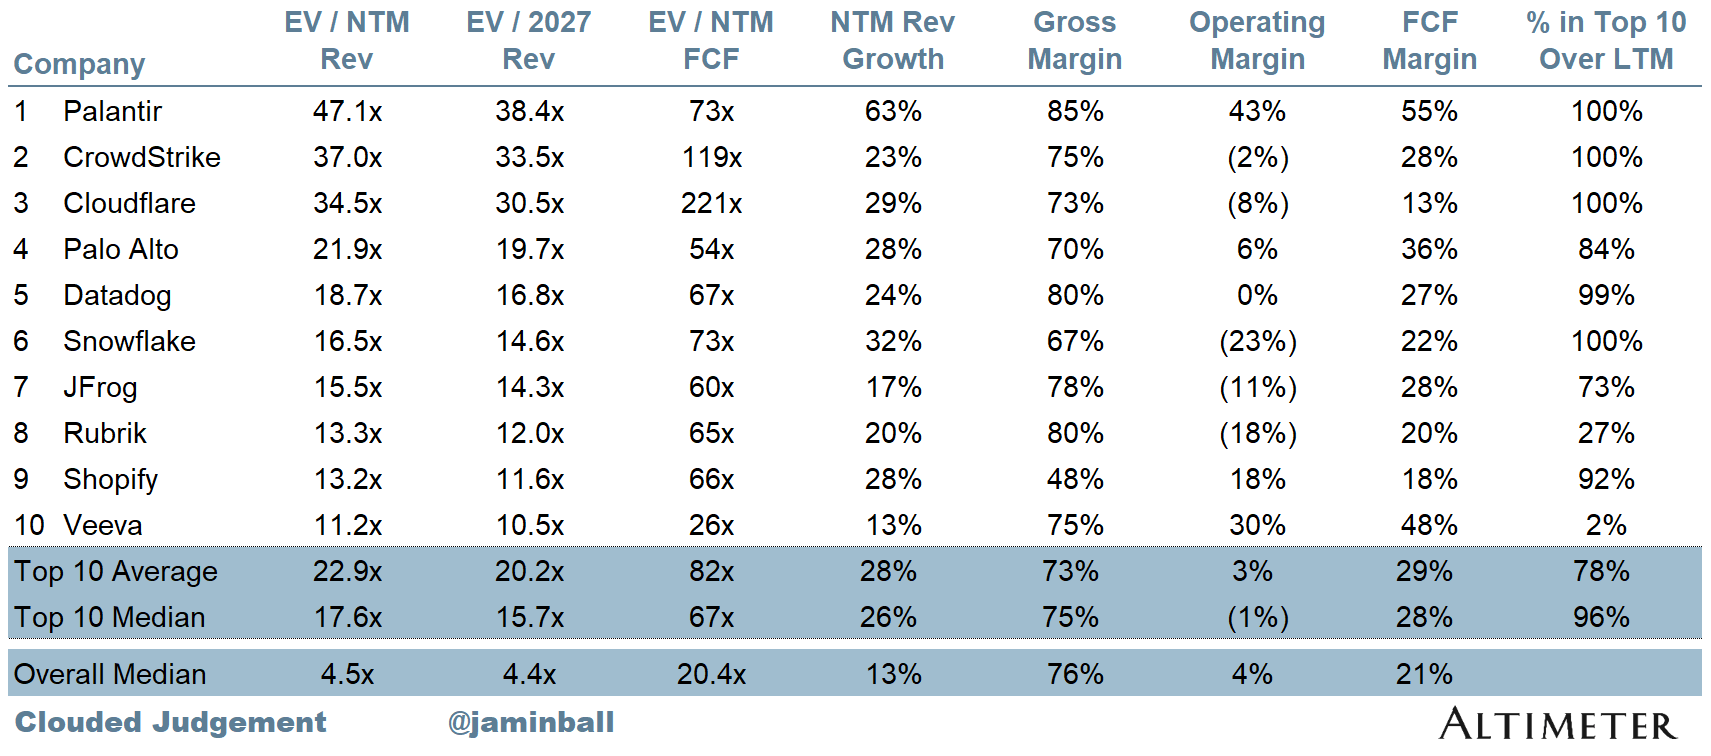
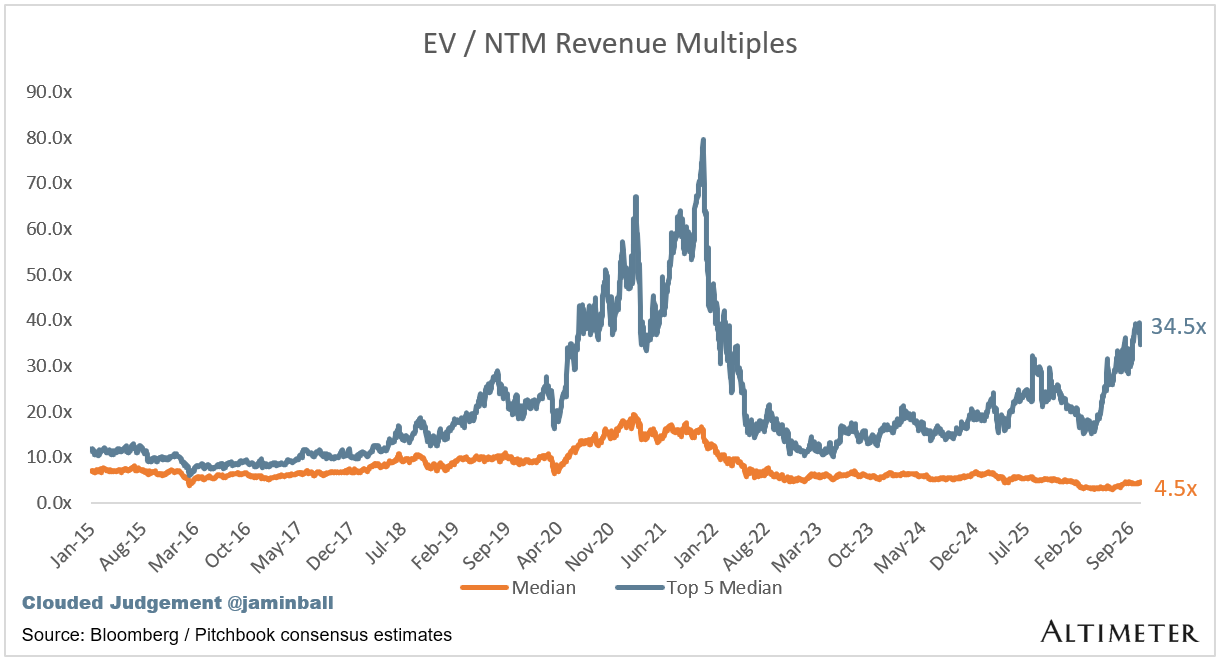
Top 10 EV / NTM Revenue Multiples
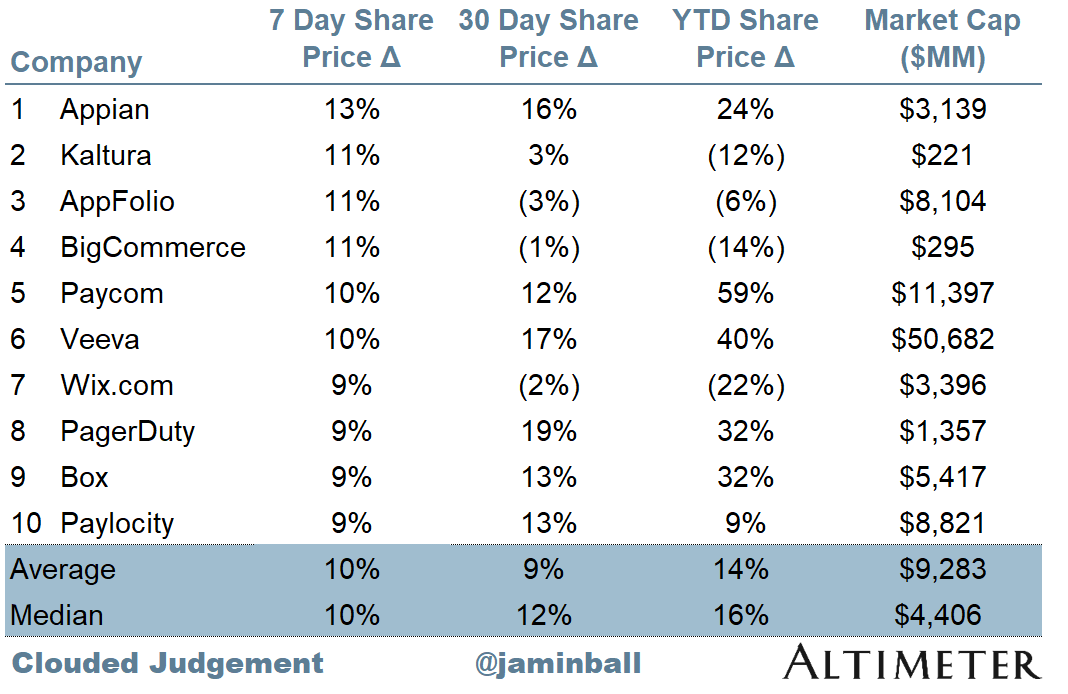
Top 10 Weekly Share Price Movement
Update on Multiples
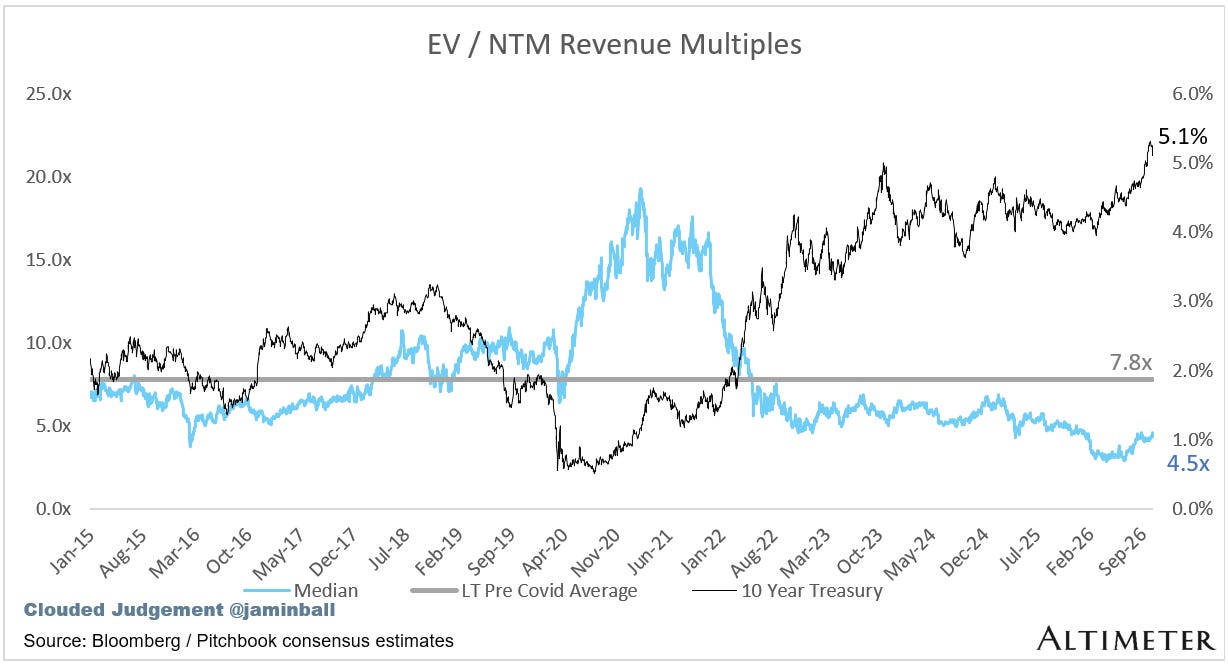
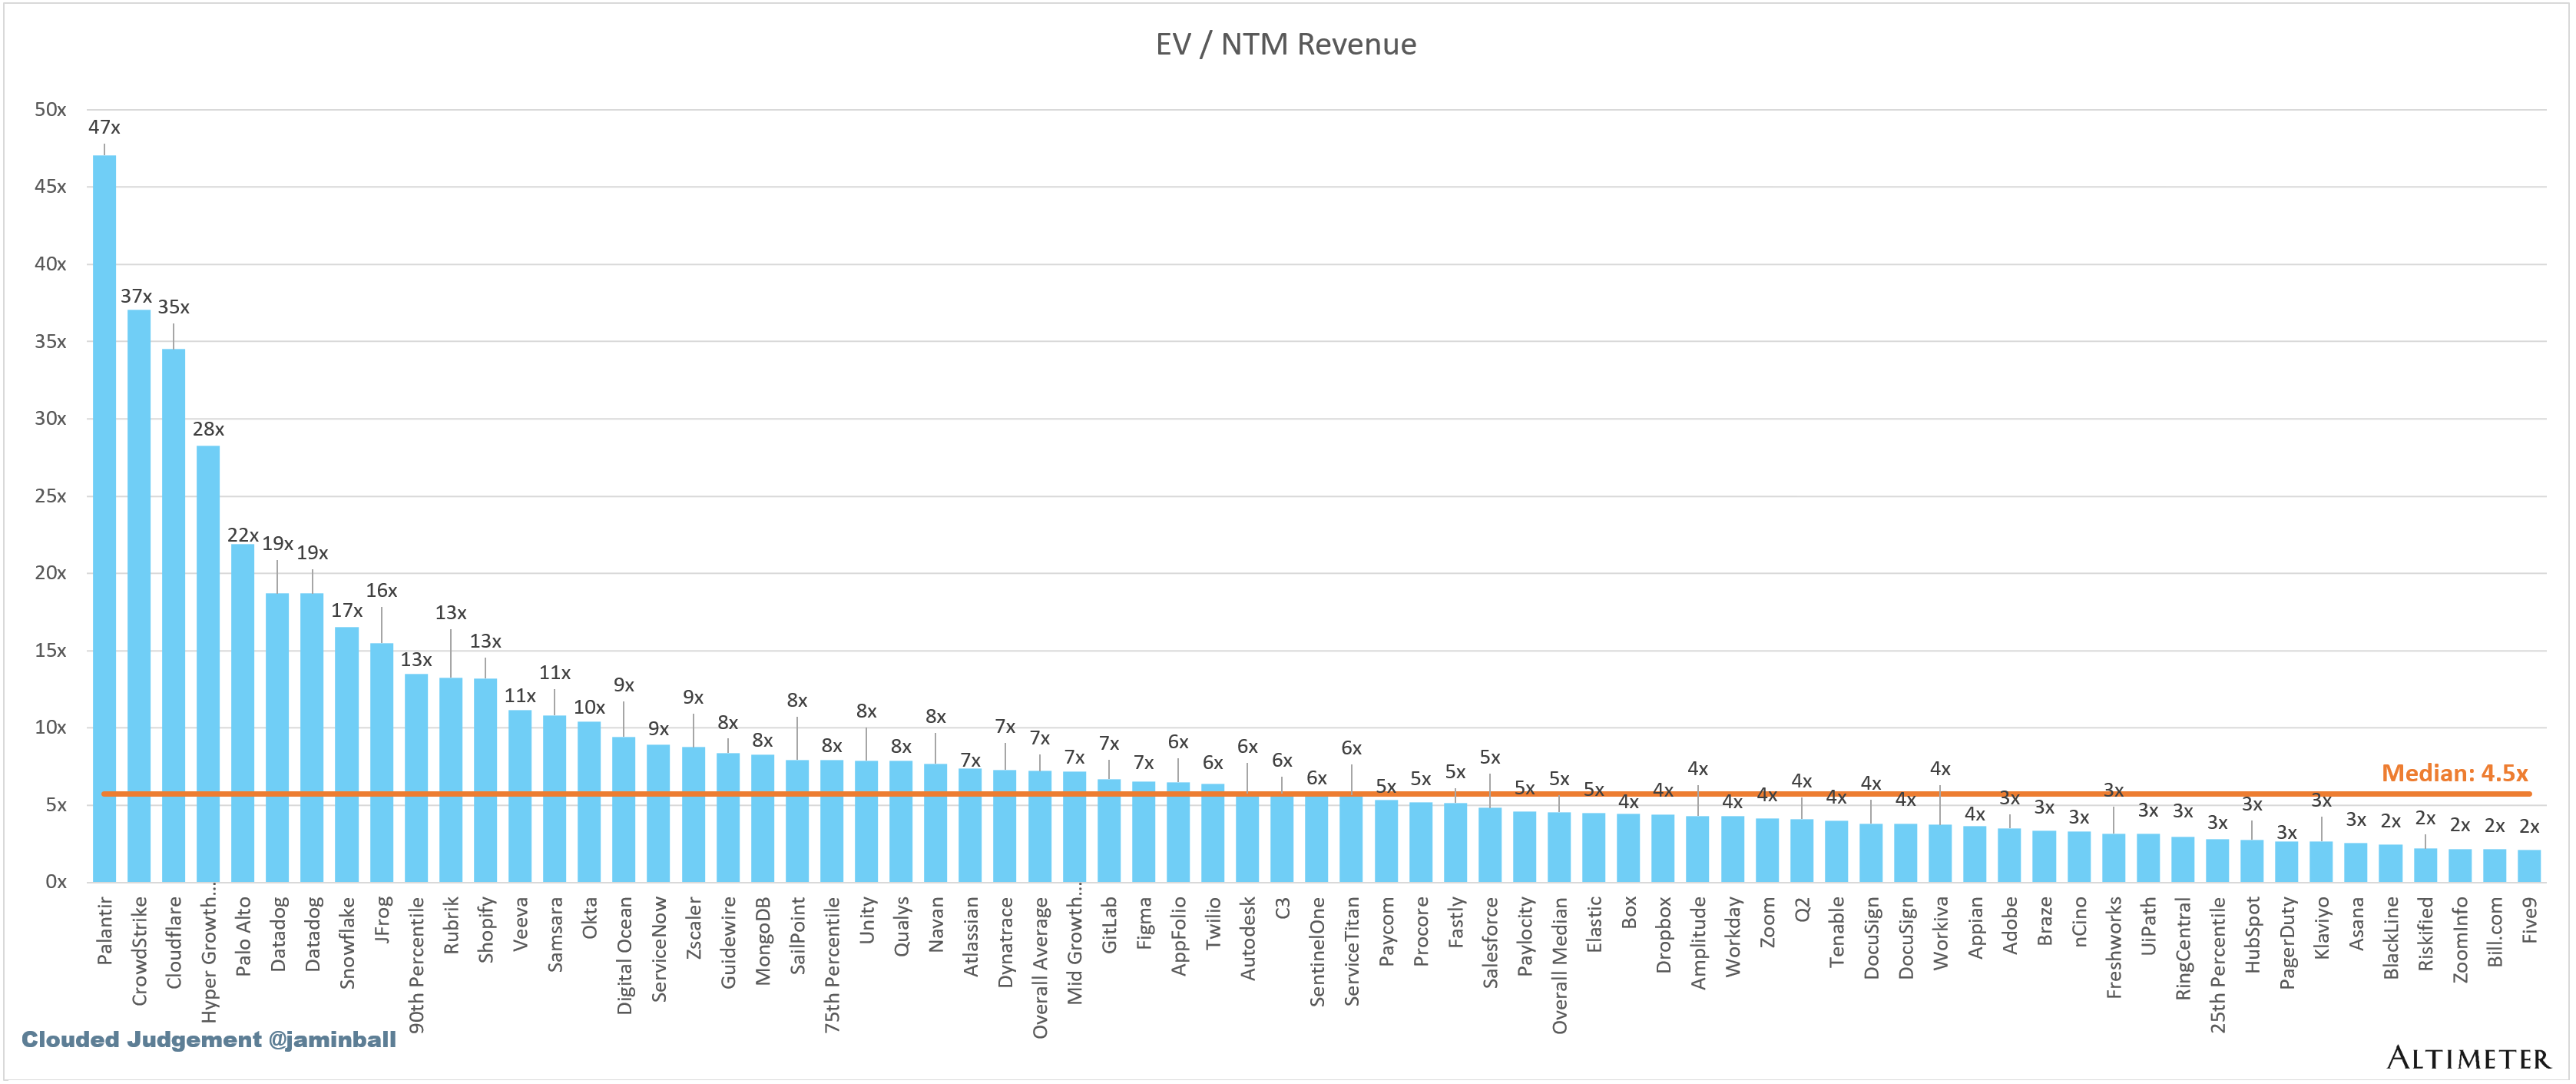
SaaS businesses are generally valued on a multiple of their revenue - in most cases the projected revenue for the next 12 months. Revenue multiples are a shorthand valuation framework. Given most software companies are not profitable, or not generating meaningful FCF, it’s the only metric to compare the entire industry against. Even a DCF is riddled with long term assumptions. The promise of SaaS is that growth in the early years leads to profits in the mature years. Multiples shown below are calculated by taking the Enterprise Value (market cap + debt - cash) / NTM revenue.
Overall Stats:
Overall Median: 4.5x
Top 5 Median: 34.5x
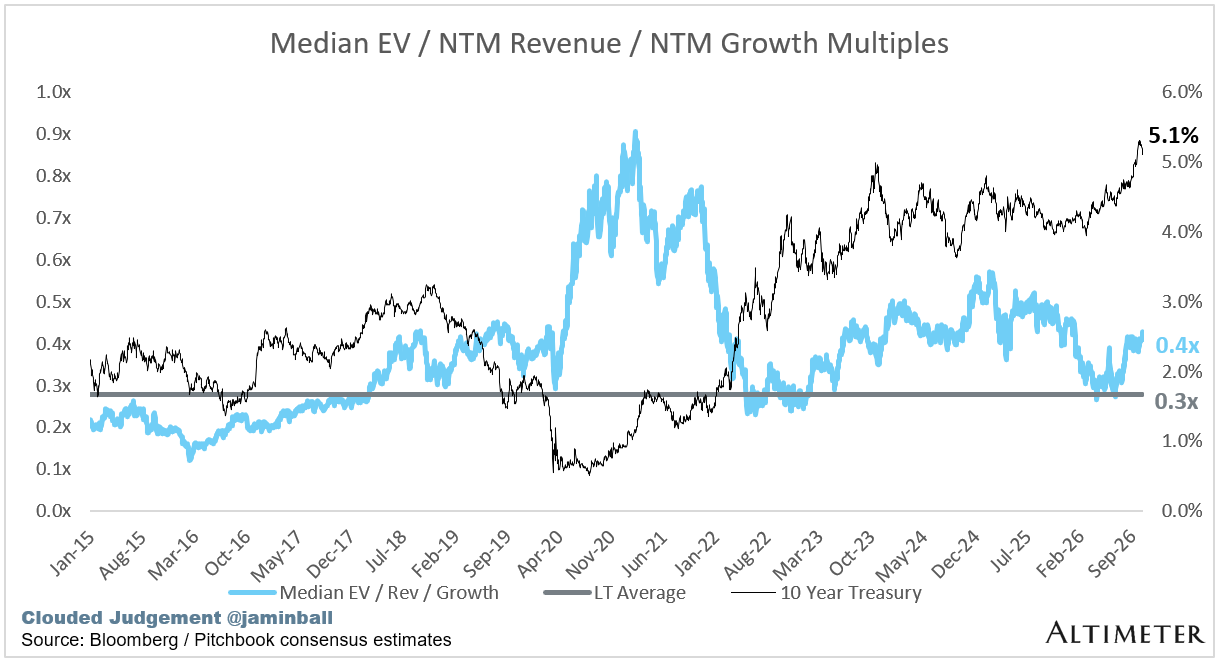
10Y: 5.1%
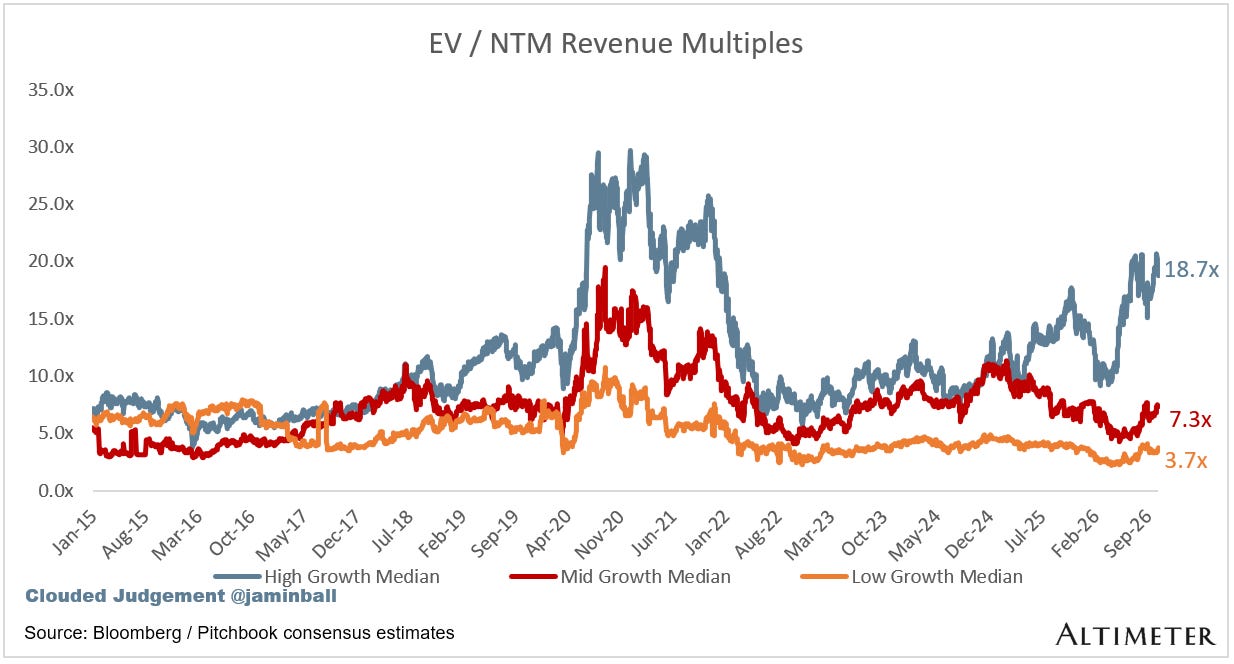
Bucketed by Growth. In the buckets below I consider high growth >22% projected NTM growth, mid growth 15%-22% and low growth <15%. I had to adjusted the cut off for “high growth.” If 22% feels a bit arbitrary, it’s because it is…I just picked a cutoff where there were ~10 companies that fit into the high growth bucket so the sample size was more statistically significant
High Growth Median: 18.7x
Mid Growth Median: 7.3x
Low Growth Median: 3.7x
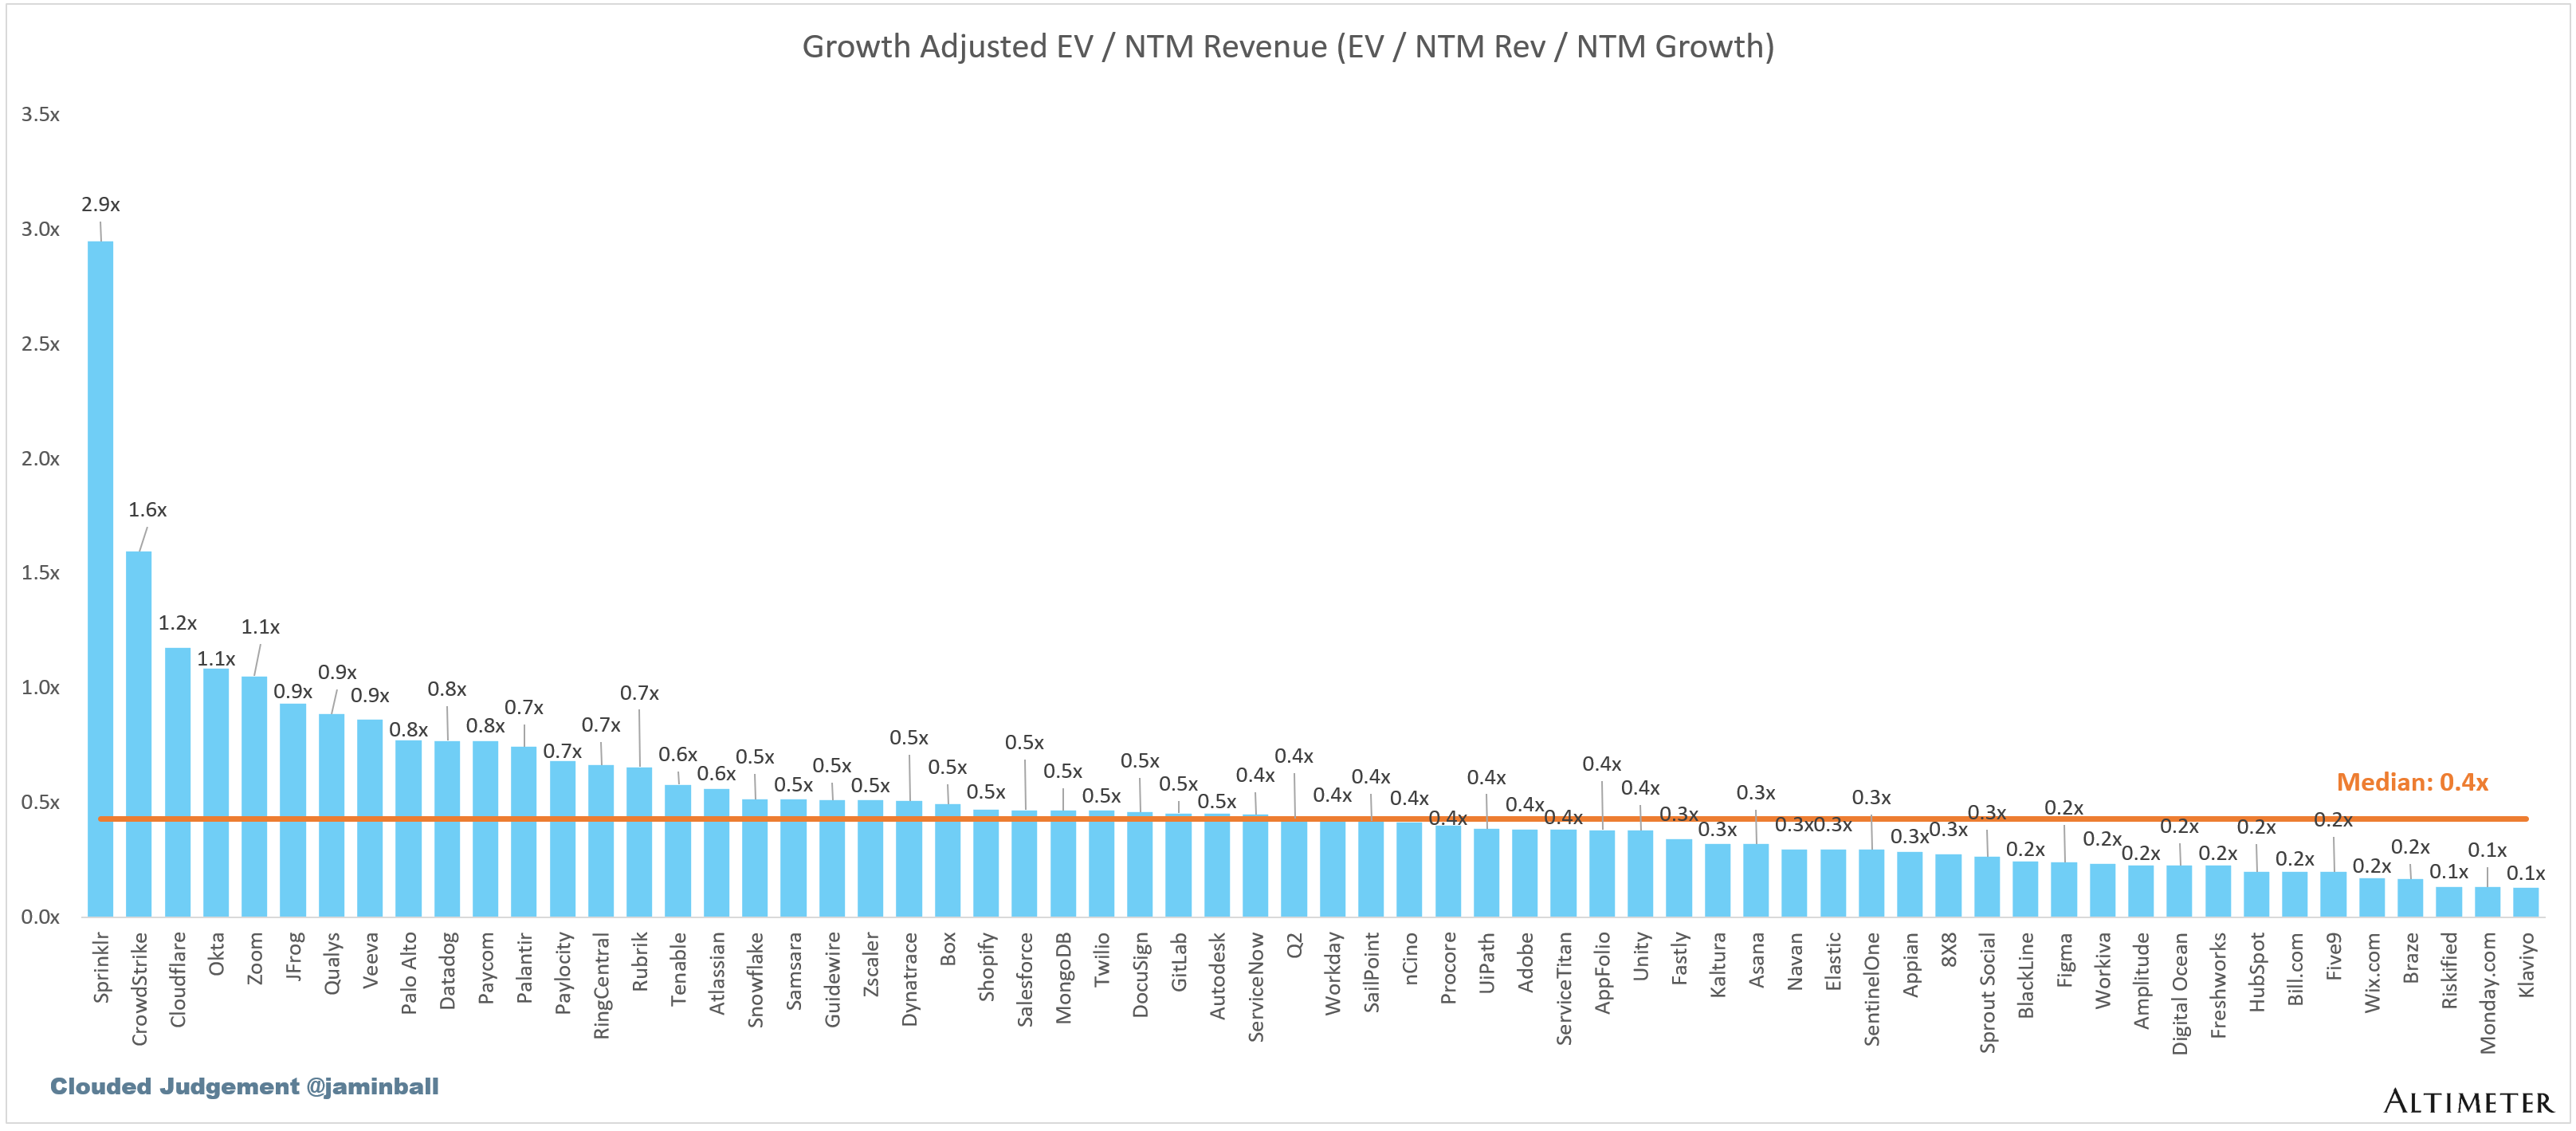
EV / NTM Rev / NTM Growth
The below chart shows the EV / NTM revenue multiple divided by NTM consensus growth expectations. So a company trading at 20x NTM revenue that is projected to grow 100% would be trading at 0.2x. The goal of this graph is to show how relatively cheap / expensive each stock is relative to its growth expectations.
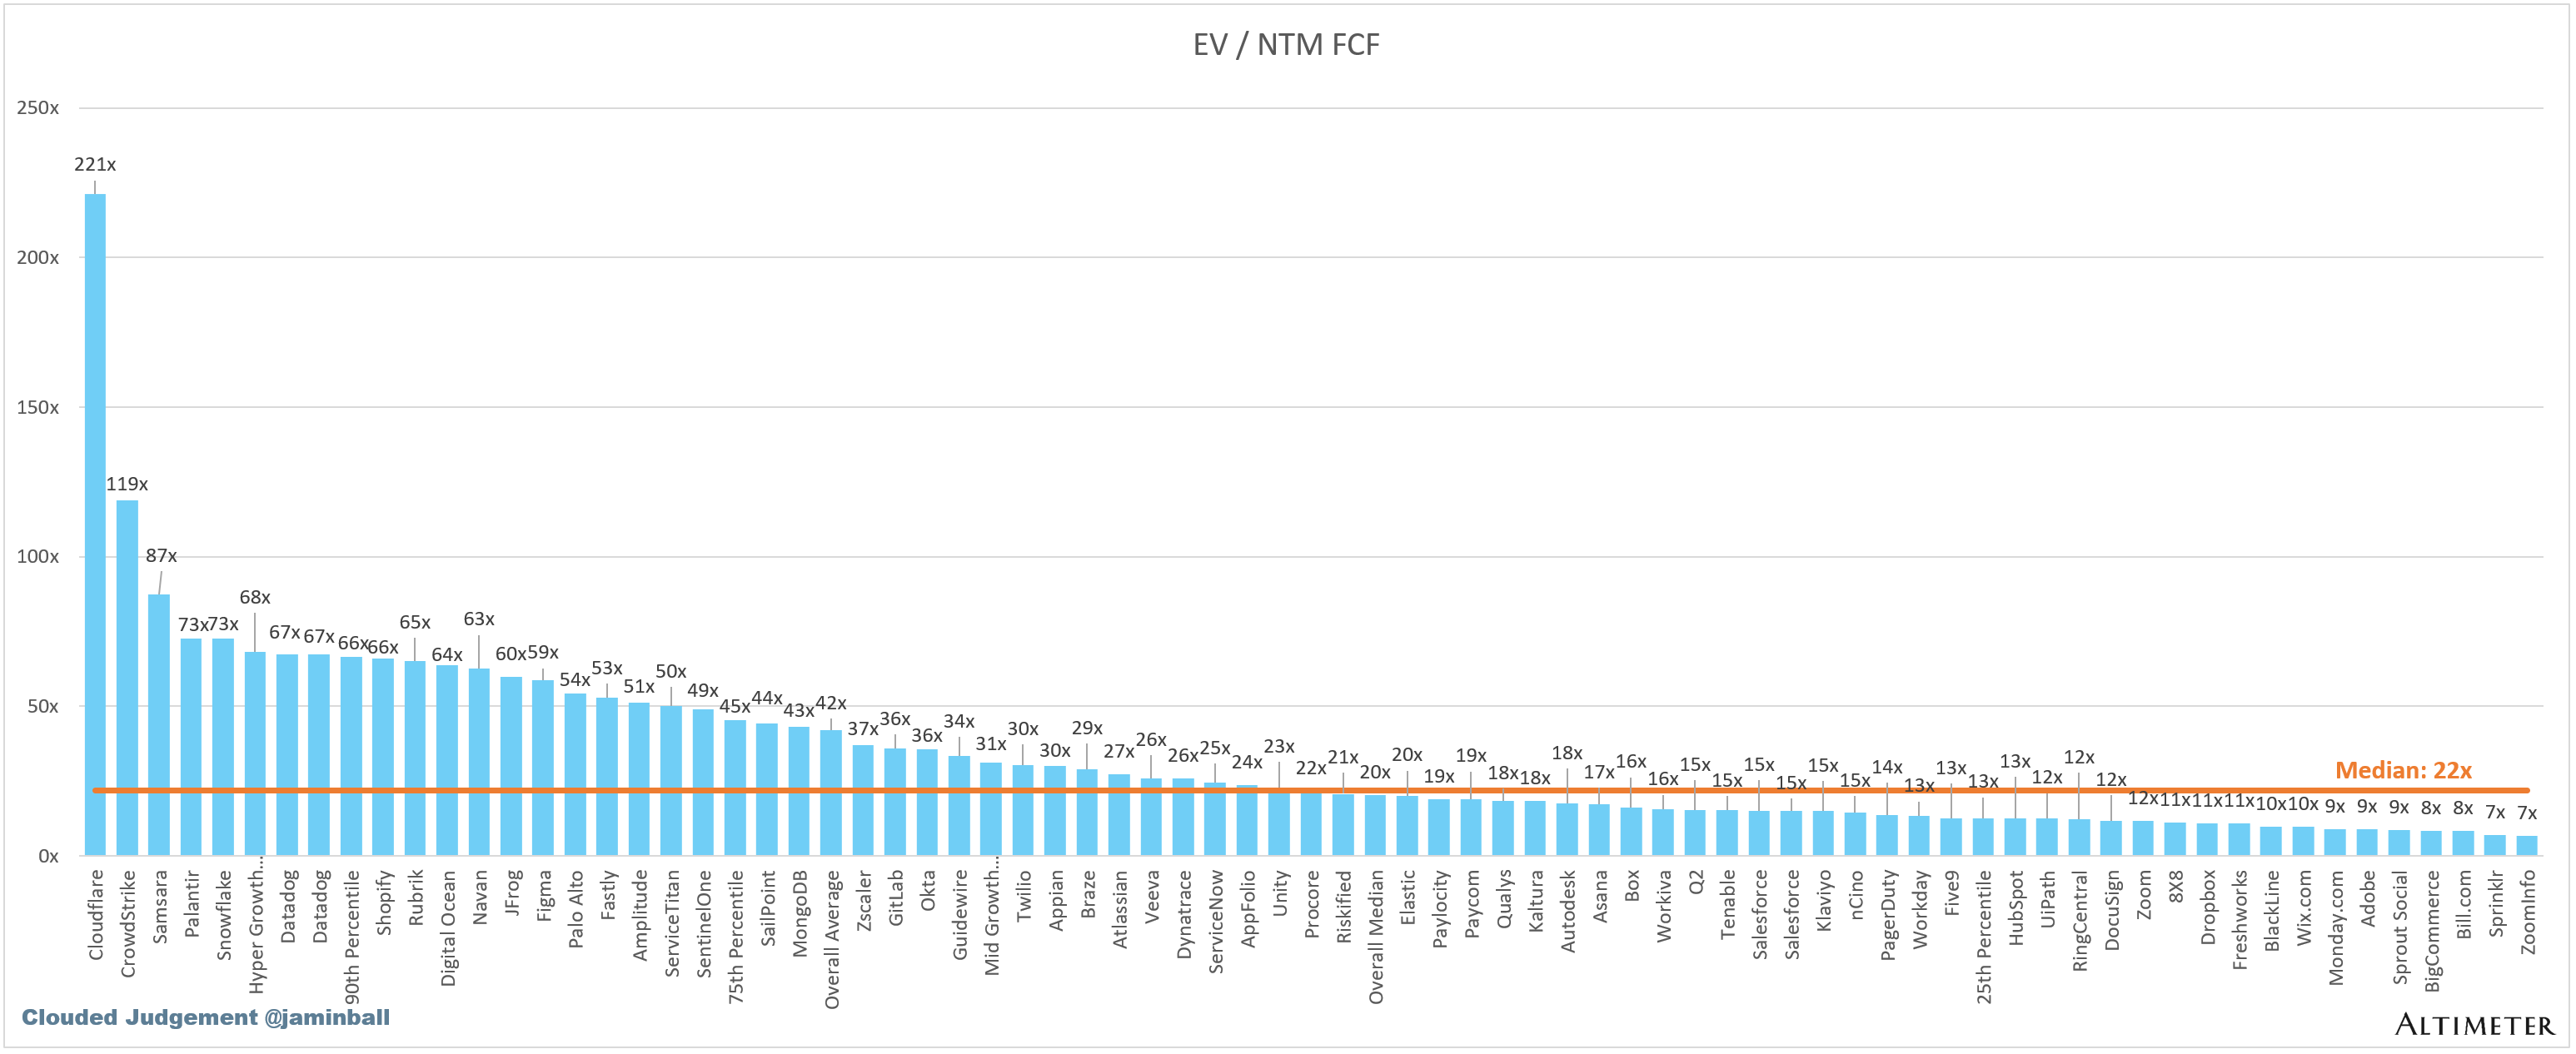
EV / NTM FCF
The line chart shows the median of all companies with a FCF multiple >0x and <100x. I created this subset to show companies where FCF is a relevant valuation metric.
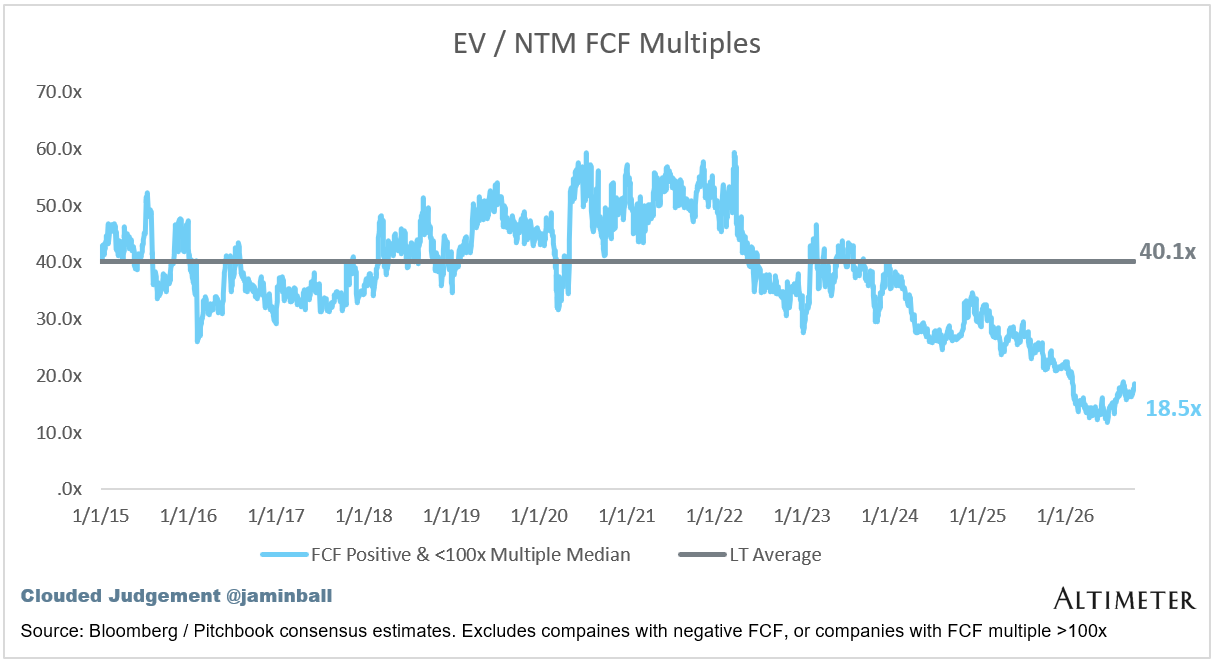
Companies with negative NTM FCF are not listed on the chart
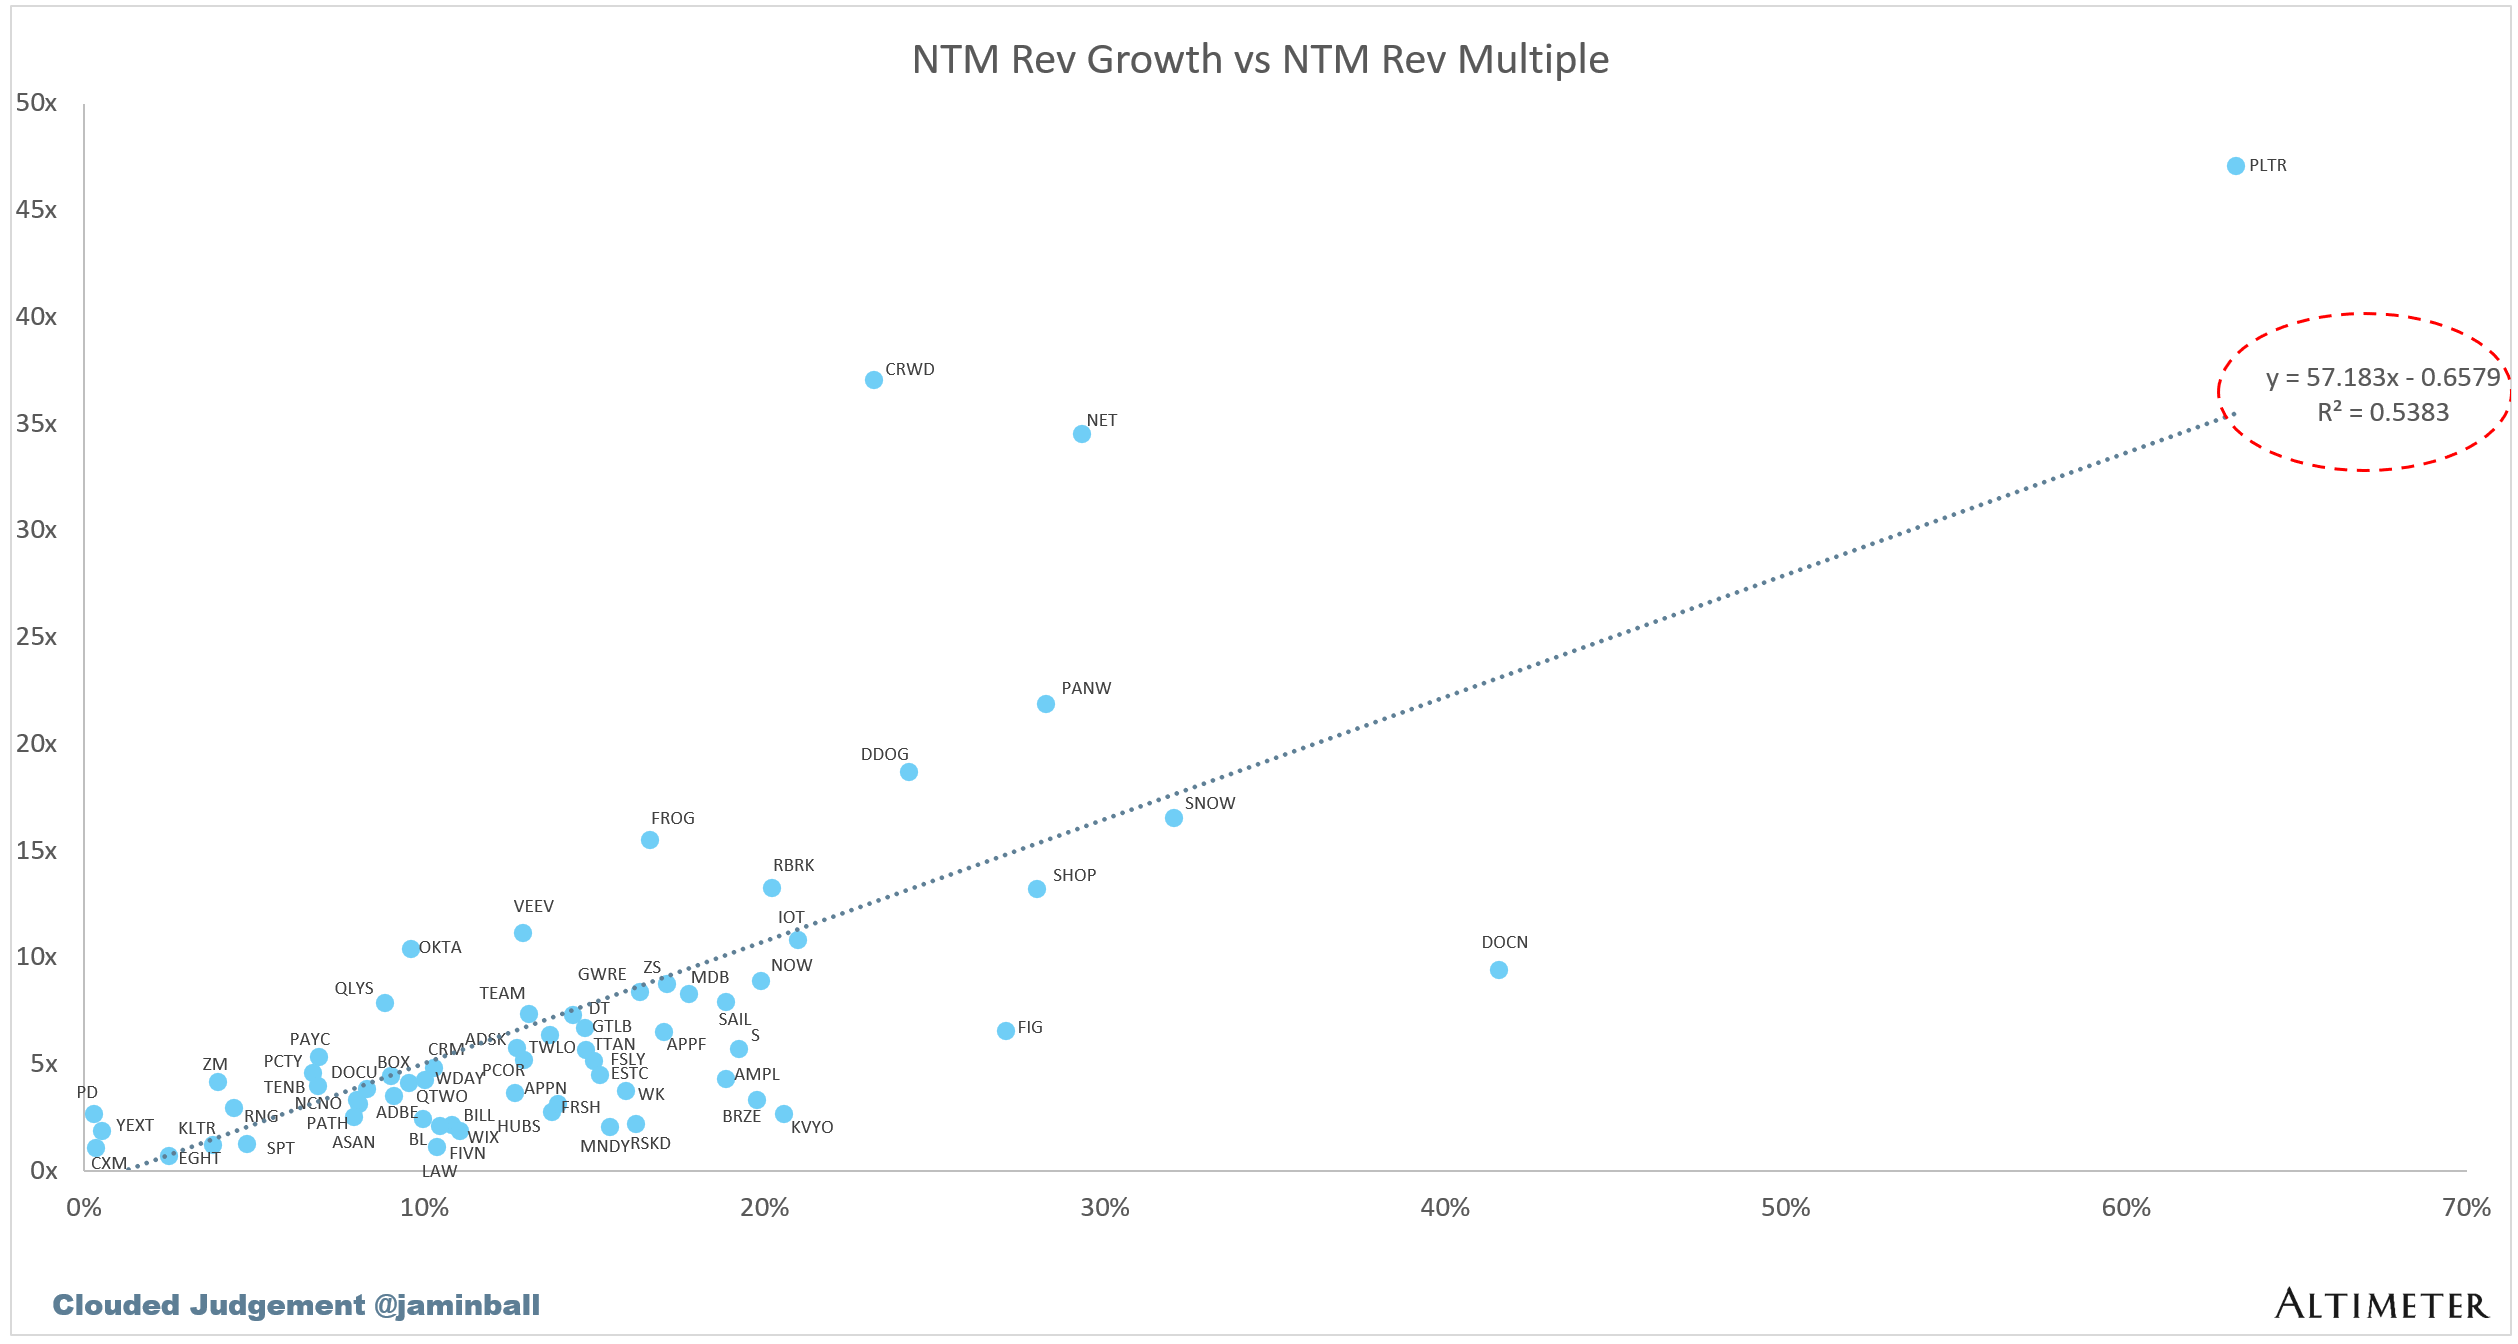
Scatter Plot of EV / NTM Rev Multiple vs NTM Rev Growth
How correlated is growth to valuation multiple?
Operating Metrics
Median NTM growth rate: 13%
Median LTM growth rate: 16%
Median Gross Margin: 76%
Median Operating Margin 4%
Median FCF Margin: 21%
Median Net Retention: 110%
Median CAC Payback: 31 months
Median S&M % Revenue: 34%
Median R&D % Revenue: 22%
Median G&A % Revenue: 13%
Comps Output
Rule of 40 shows rev growth + FCF margin (both LTM and NTM for growth + margins). FCF calculated as Cash Flow from Operations - Capital Expenditures
GM Adjusted Payback is calculated as: (Previous Q S&M) / (Net New ARR in Q x Gross Margin) x 12. It shows the number of months it takes for a SaaS business to pay back its fully burdened CAC on a gross profit basis. Most public companies don’t report net new ARR, so I’m taking an implied ARR metric (quarterly subscription revenue x 4). Net new ARR is simply the ARR of the current quarter, minus the ARR of the previous quarter. Companies that do not disclose subscription rev have been left out of the analysis and are listed as NA.
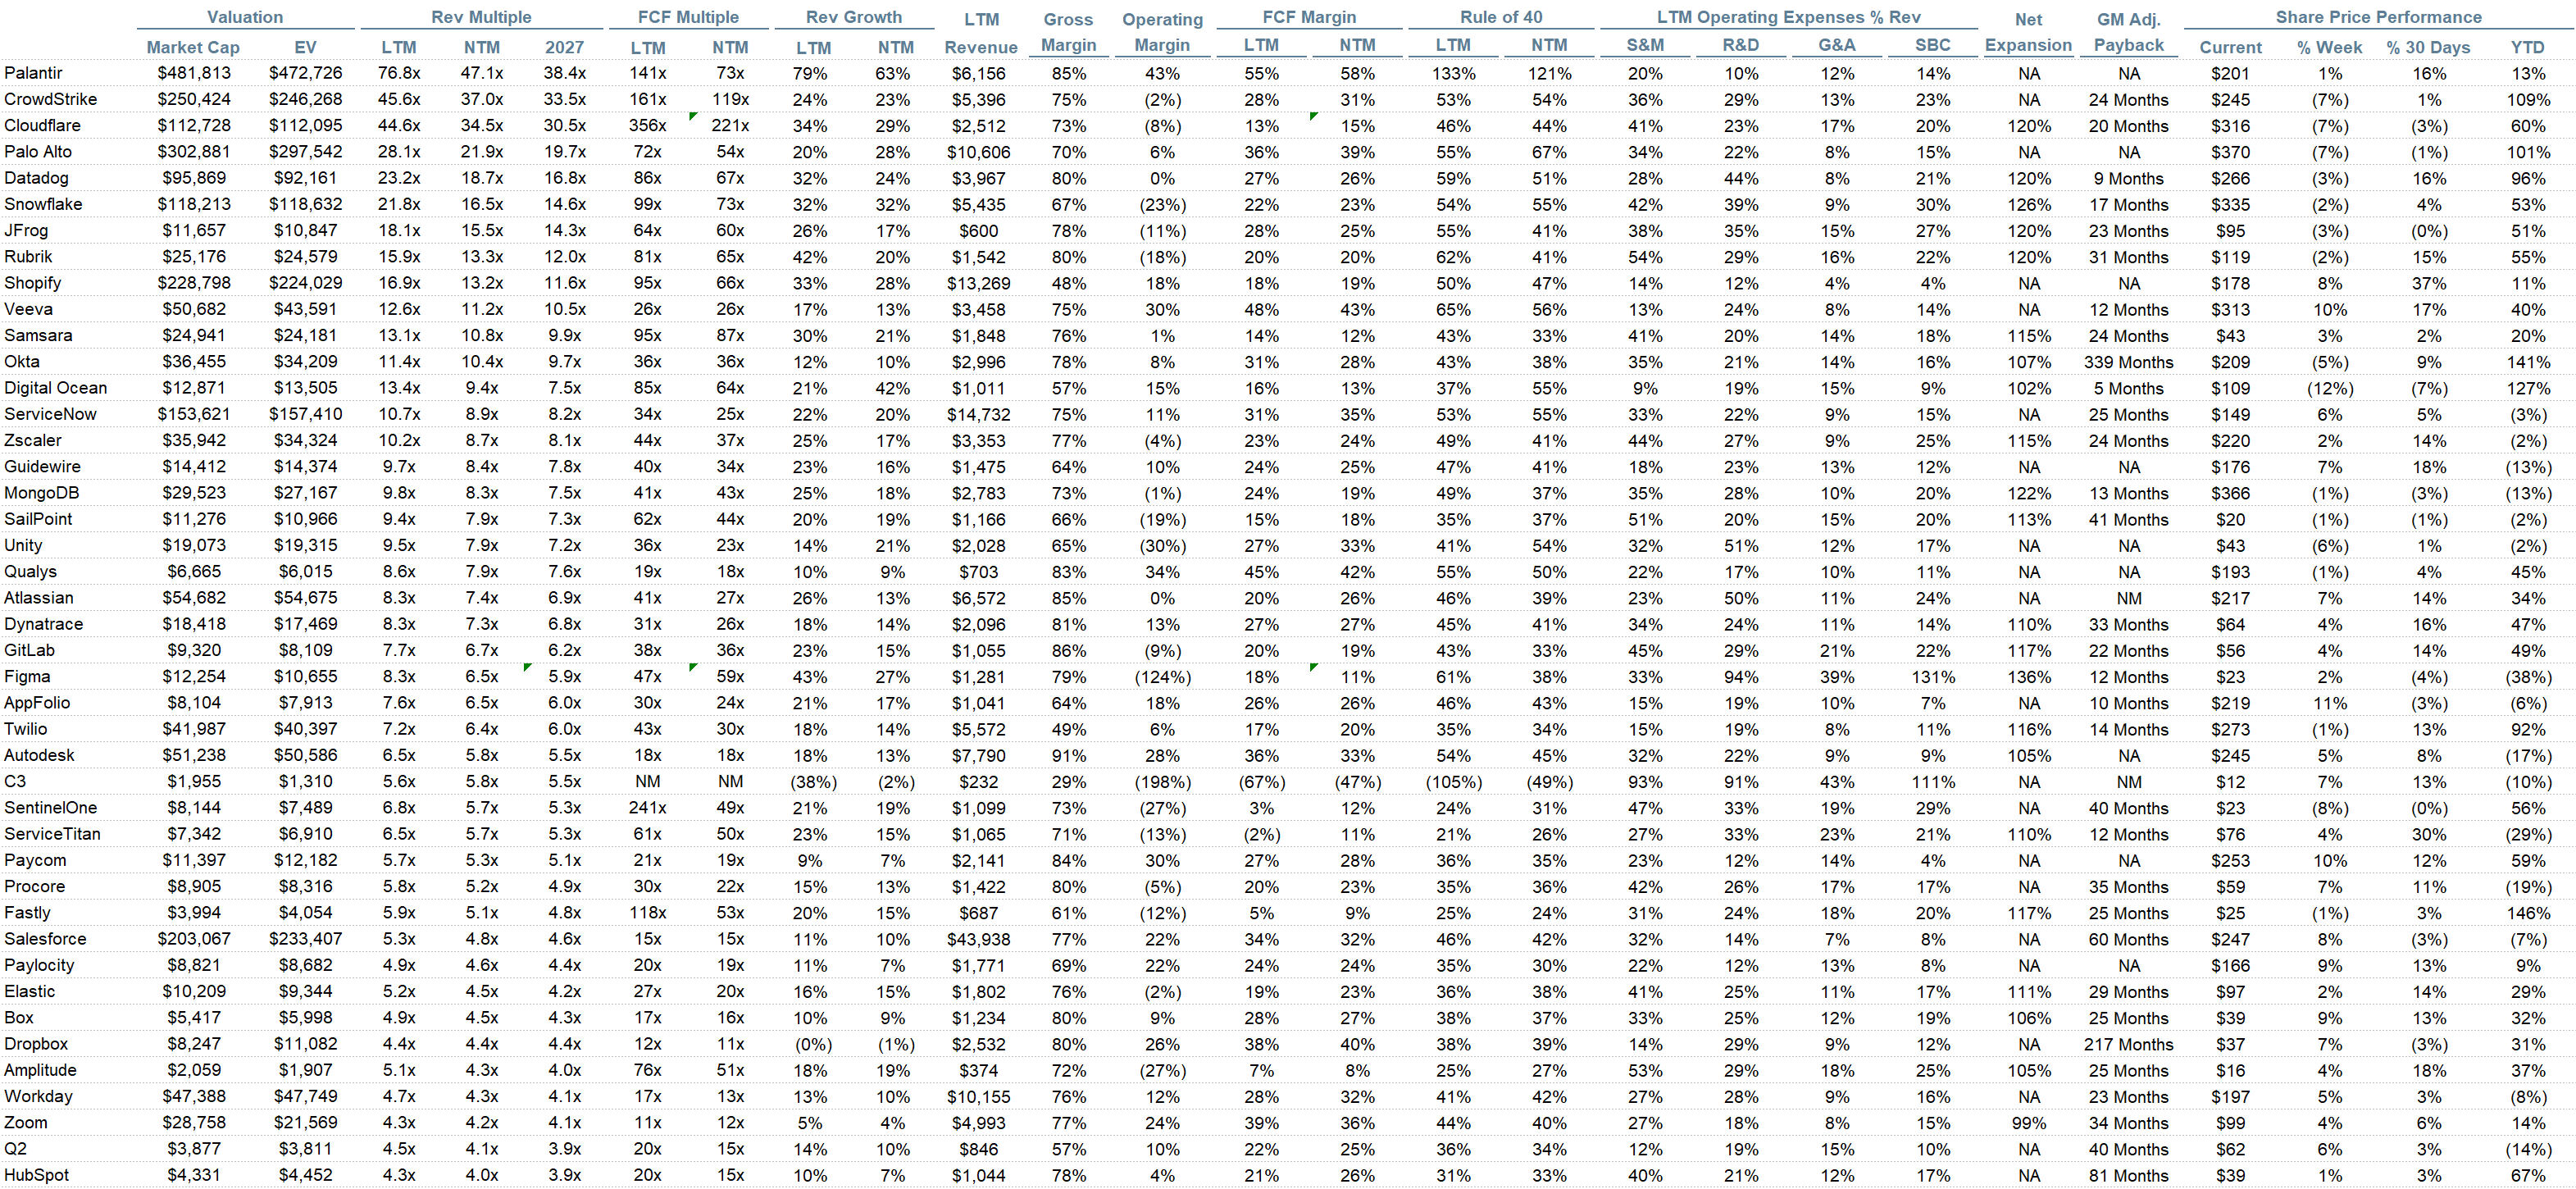
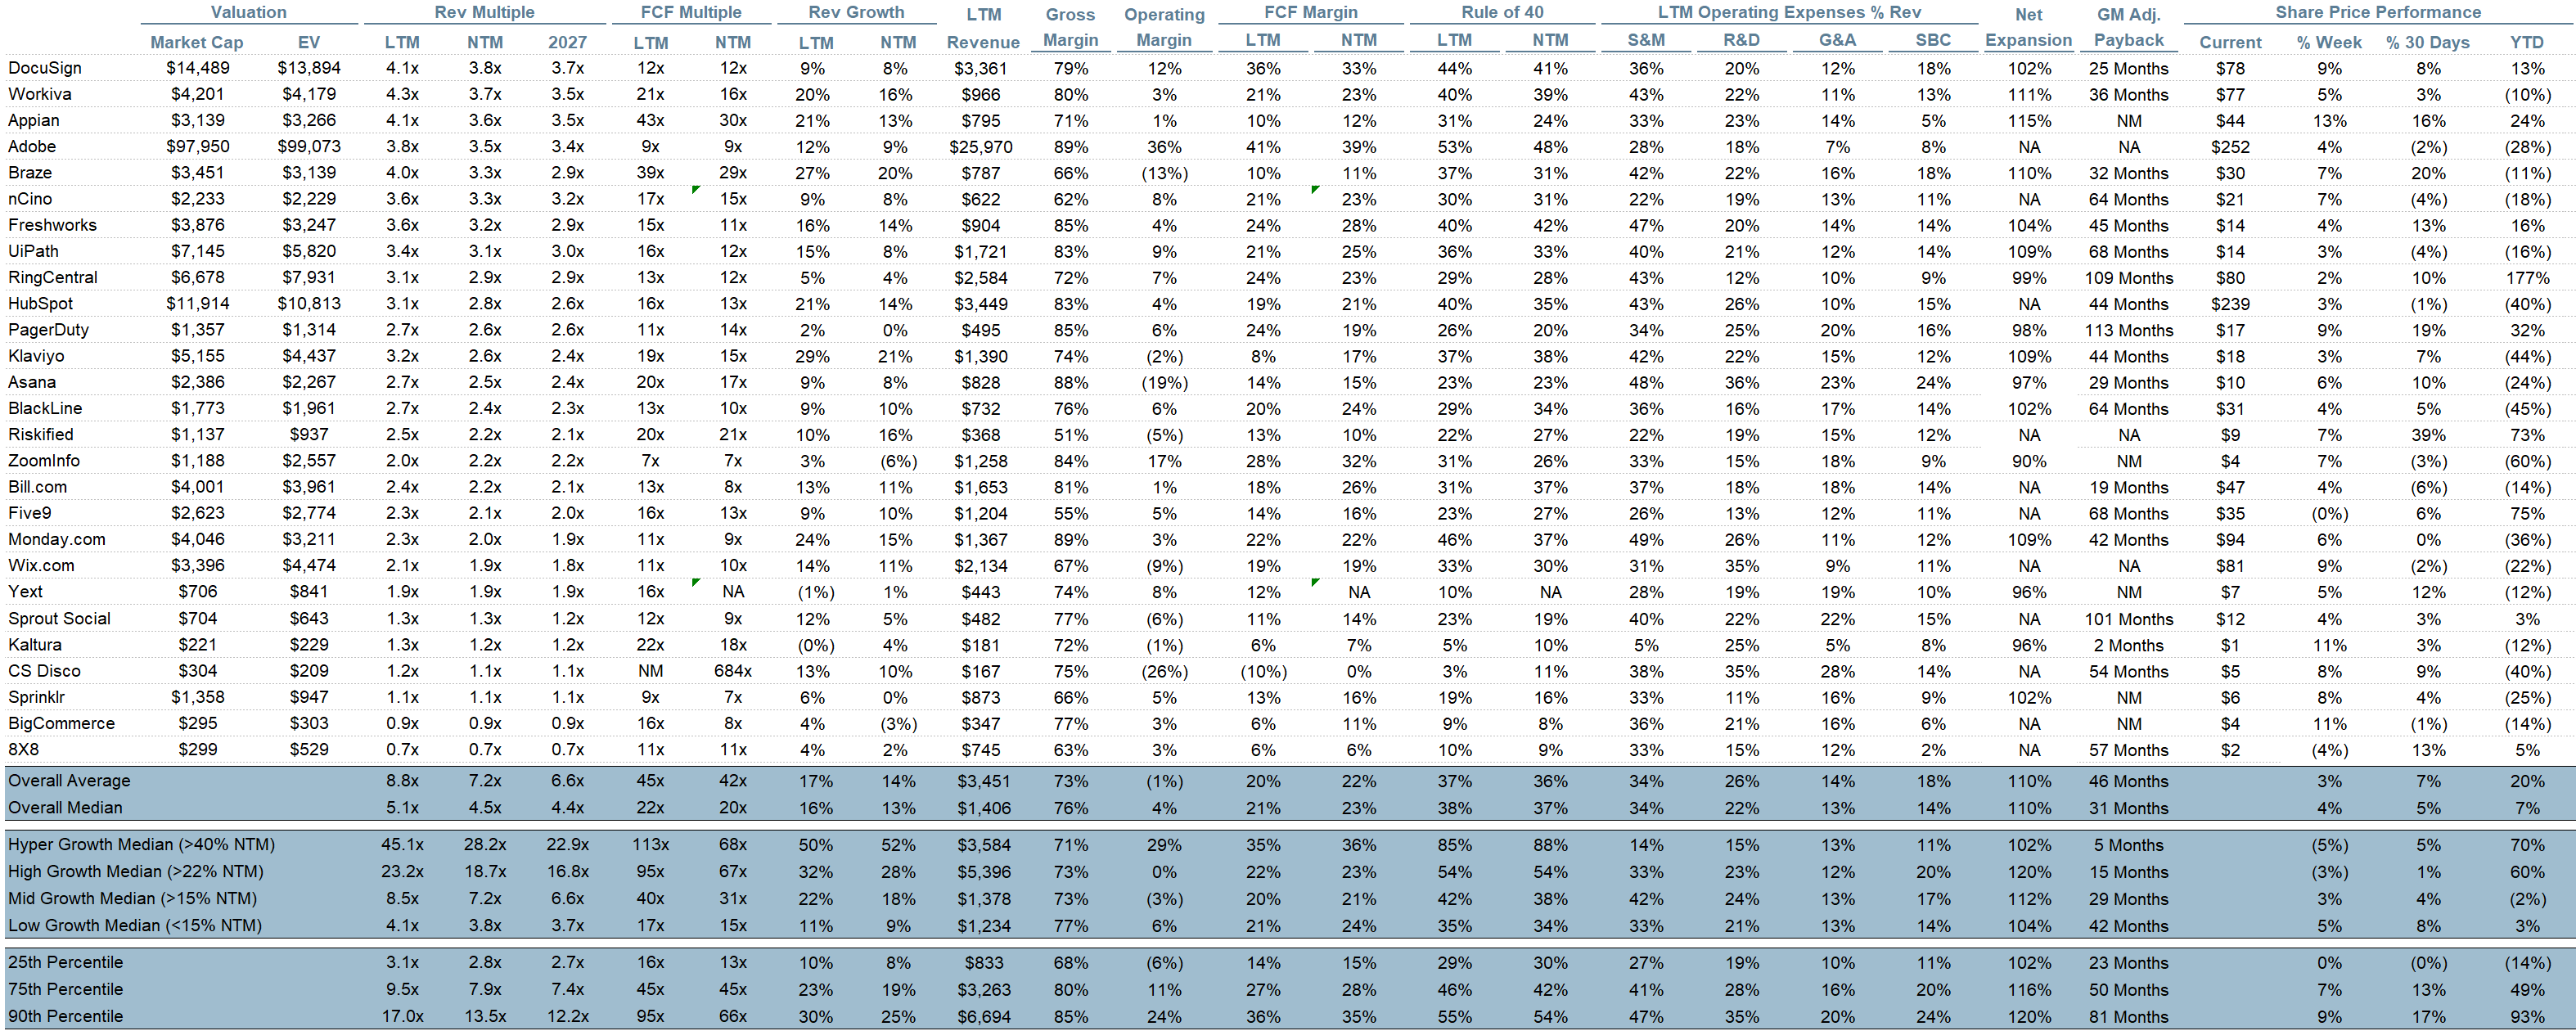
Sources used in this post include Bloomberg, Pitchbook and company filings
The information presented in this newsletter is the opinion of the author and does not necessarily reflect the view of any other person or entity, including Altimeter Capital Management, LP (”Altimeter”). The information provided is believed to be from reliable sources but no liability is accepted for any inaccuracies. This is for information purposes and should not be construed as an investment recommendation. Past performance is no guarantee of future performance. Altimeter is an investment adviser registered with the U.S. Securities and Exchange Commission. Registration does not imply a certain level of skill or training. Altimeter and its clients trade in public securities and have made and/or may make investments in or investment decisions relating to the companies referenced herein. The views expressed herein are those of the author and not of Altimeter or its clients, which reserve the right to make investment decisions or engage in trading activity that would be (or could be construed as) consistent and/or inconsistent with the views expressed herein.
This post and the information presented are intended for informational purposes only. The views expressed herein are the author’s alone and do not constitute an offer to sell, or a recommendation to purchase, or a solicitation of an offer to buy, any security, nor a recommendation for any investment product or service. While certain information contained herein has been obtained from sources believed to be reliable, neither the author nor any of his employers or their affiliates have independently verified this information, and its accuracy and completeness cannot be guaranteed. Accordingly, no representation or warranty, express or implied, is made as to, and no reliance should be placed on, the fairness, accuracy, timeliness or completeness of this information. The author and all employers and their affiliated persons assume no liability for this information and no obligation to update the information or analysis contained herein in the future.
The diffusion gap framing is a helpful way to separate model capability from actual revenue. The PNC figure of only about 2% of US households paying for AI sits awkwardly next to capex commitments sized for something much larger. I'd say the capex case rests less on power users spending more and more of the time, and more on whether enterprise adoption closes the gap, since enterprise contracts tend to scale differently from consumer subscriptions. Which of the two do you find more convincing as the main driver, and what would you watch to tell them apart?
The browser and Maps examples make me think the next step goes further, and the average user may never "use" AI much at all. They'll hand a decision to an agent, and the agent does the using. If diffusion happens that way, the revenue shows up as agents spending on people's behalf rather than the 2% of households with a subscription becoming 20%, so who captures it: the model owners, or whoever owns the agent the user trusts?